Description
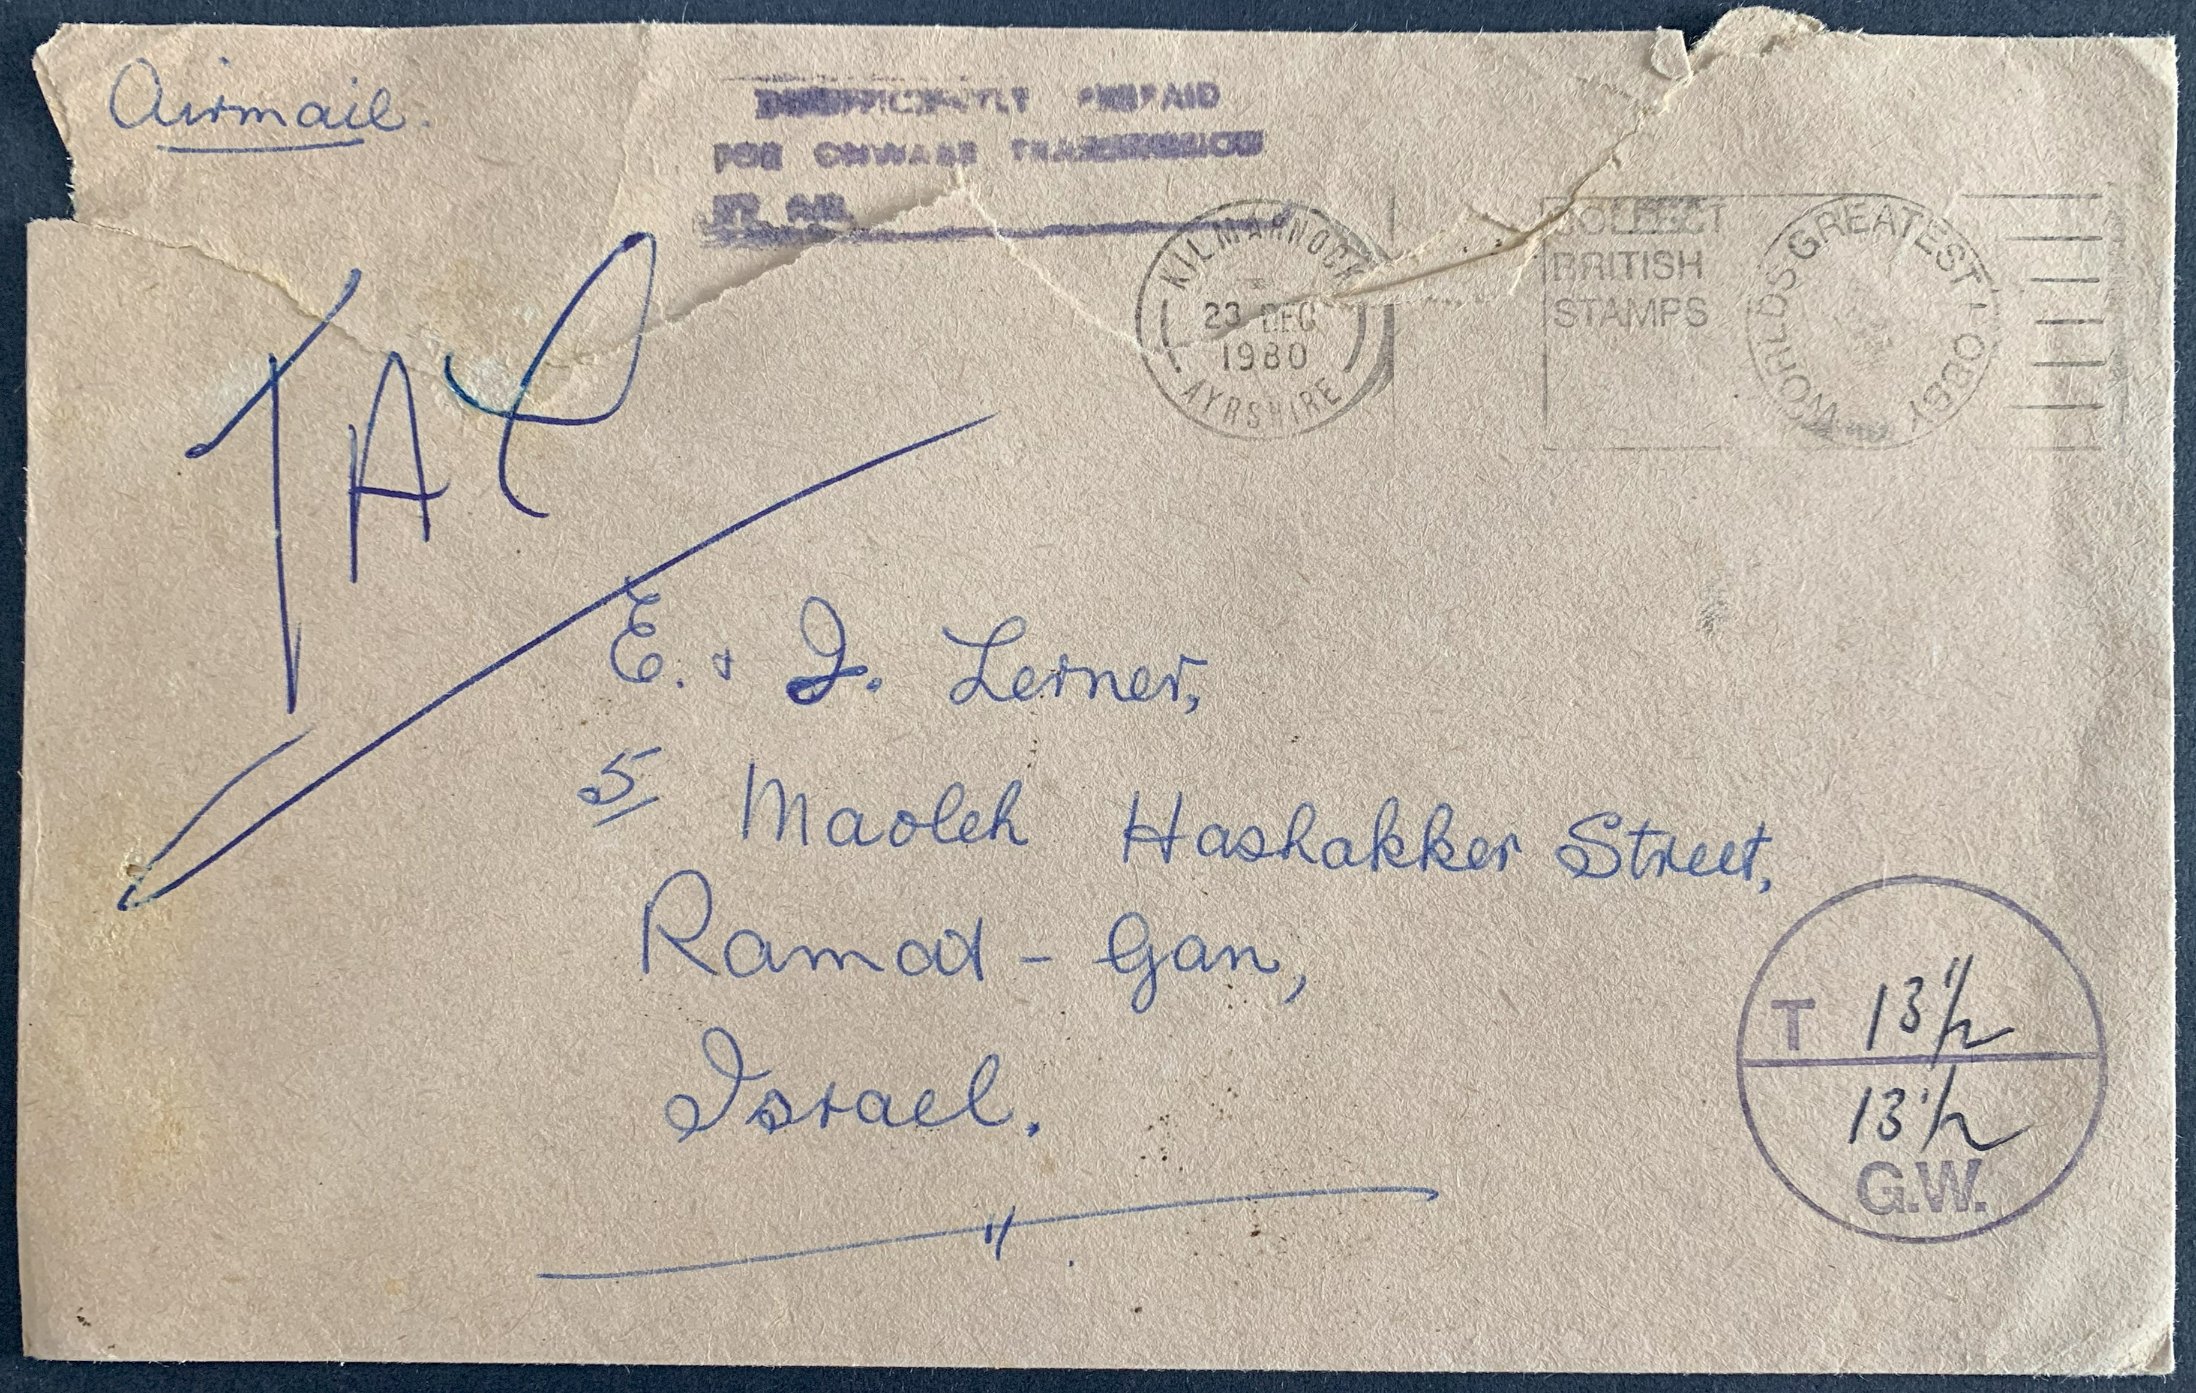
Incoming British postage dues during revised taxe fraction era: 13 Dec 1980 postmarked 'air mail' endorsed cover, sent from KILMARNOCK to RAMAT GAN - but posted unfranked, though tied by machine cancel (likely entered unfranked into a letter box and then processed in bulk). Subsequently manuscript marked for postage dues "TAX" & tied by "DEFICIENTLY PREPAID FOR ONWARD TRANSMISSION BY AIR" instructional handstamp (implying onward transmission by surface mail) + circular taxe fraction handstamp, written out as 13.5 / 13.5. In this period of the revised taxe fraction method (as of 1 Jan 1976), the deficient postage alone was written in the numerator (no longer double the amount as the tax) and the sending country's base letter surface postage rate was written in the denominator, here as sent by default via surface mail, this was written as 13.5 pence deficiency for the base 20 grams 13.5 pence surface mail rate (as per postage rates of 4 Feb. 1980), rather than a higher deficient postage amount if sent by airmail; this calculation was to be multiplied in the receiving country by its equivalent surface postage rate plus the addition of a 'handling fee' for mail sent incorrectly franked.
In Israel the post office would have multiplied the taxe fraction by its period surface mail rate of 17 Shekels (as of 1 May 1980), yielding an equivalent deficiency in local currency of 17 Shekels, and then add in its handling fee, which as of 1 May 1980 was 9.50 ILS; this would have yielded a total postage due charge of 26.50 ILS. Although the cover does not bear any postage dues franks the tax was likely paid in cash. Opened roughly at top, complete.
Interesting postal handling by the British post office, which chose to nevertheless transmit the unfranked letter rather than returning it to the sender for postage - likely because there is no return address on the cover: at various times different postal administrations (including Israel's) would return insufficiently franked mail to the sender if it was underfranked by 50% or more of the necessary postage.